How to track income and expenses for your household: the categories, the routine, and what to do with the numbers
A simple way to track what comes in and goes out at home: which categories to use, how often to update, and how to read a month of real numbers.
Tracking income and expenses sounds like accounting. At home, it's really just answering one question: where did the money go this month?
Once you can answer that, every other money decision gets easier. Here's a simple way to do it that doesn't take over your evenings.
Start with income
Income is the easy side, but write down all of it, not just the main paycheque.
- Take-home pay from each job, after tax and deductions
- Side income: freelance work, selling things online, tips
- Child benefits, tax refunds, government payments
- Interest, gifts, money paid back to you
Use what actually lands in your account. Your gross salary isn't money you can spend.
Pick categories that fit your life
Too few categories and you learn nothing. Too many and you'll stop tracking. Somewhere between 10 and 15 is a good place to start for most households. A common set:
- Housing: rent or mortgage, property tax, condo fees
- Utilities: power, heat, water
- Phone and internet
- Groceries
- Dining out and takeout
- Transportation: gas, transit, parking, car insurance
- Kids: childcare, activities, school costs
- Health: prescriptions, dental, glasses
- Subscriptions
- Personal and household: toiletries, cleaning supplies, haircuts
- Gifts and holidays
- Savings and debt payments
Two rules make categories work. First, keep groceries separate from dining out. They're both food, but they behave very differently. Second, if a category keeps surprising you, split it. If you don't care about the detail, merge it.
How often to update
Little and often beats one big catch-up.
- A few times a week, or daily: log purchases while you still remember what they were. Five minutes, tops.
- Once a week: check that bank and card transactions match what you logged, and look at how each category is tracking.
- Once a month: compare the month to your plan. This is where the useful part happens.
If you fall behind, don't try to recreate every receipt. Pull the transactions from your bank and card statements and categorize those.
A worked month
Here's one household's month. They take home two paycheques of $2,600 each, paid twice a month, plus $400 from a side job: $5,600 in total.
| Category | Planned | Actual | Difference |
|---|---|---|---|
| Housing | $1,850 | $1,850 | $0 |
| Groceries | $750 | $860 | +$110 |
| Transportation | $400 | $365 | −$35 |
| Utilities and phone | $300 | $312 | +$12 |
| Dining out | $200 | $290 | +$90 |
| Kids | $250 | $230 | −$20 |
| Subscriptions | $60 | $75 | +$15 |
| Personal and household | $200 | $248 | +$48 |
| Total spending | $4,010 | $4,230 | +$220 |
They planned to have $5,600 − $4,010 = $1,590 left for savings and debt. They actually had $5,600 − $4,230 = $1,370. Not a disaster, but $220 short of the plan.
What to do with the numbers
The table is only useful if it changes something. Here's how to read it.
- Find the biggest gaps first. Groceries (+$110) and dining out (+$90) make up $200 of the $220. That's where to look. The +$12 on utilities isn't worth worrying about.
- Ask if it was a one-off or a pattern. One expensive grocery month might be a birthday party. Three in a row means the plan is wrong, not you. Raise the plan to something real.
- Watch pairs of categories. Dining out and groceries often move together: a busy month means more takeout. If one goes up and the other goes down, that's fine.
- Look at the year, not just the month. After a few months, you'll see which categories are steady and which swing. The swingy ones need a buffer.
- Decide what the "left over" is for. Money with no job tends to disappear. Give the $1,370 a purpose: an emergency fund, a sinking fund, extra on a debt.
If debt is part of the picture, our post on debt snowball vs avalanche shows what an extra $200 a month can do. If you're paid every two weeks rather than twice a month, see budgeting around biweekly paycheques, since some months will have three paycheques.
This is a way to see your spending clearly, not financial advice.
A tracker that does the sorting for you
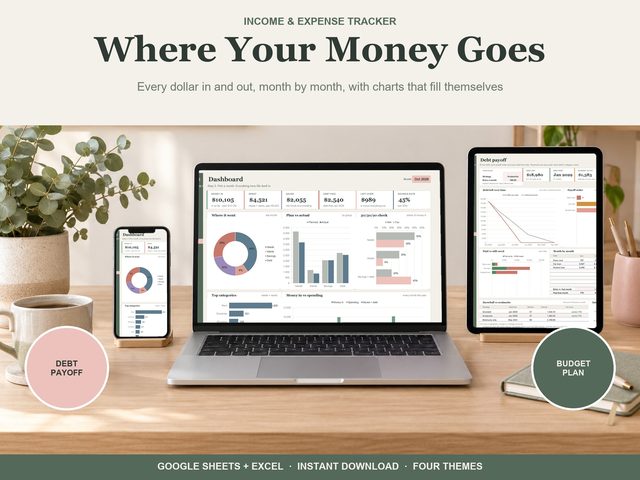
Our Income and Expense Tracker for Google Sheets and Excel is built for exactly this routine. Log what comes in and goes out on Transactions (10,000 rows, with a duplicate check), put repeating paycheques and bills on Recurring once, and set a monthly budget per category on Plan.
The dashboard then fills itself in: pick a month to see six key numbers, charts and every category planned vs real, like the table above. There's a tab for each month from January to December with bills to tick as you pay them, a Year view and Insights showing every category every month and where your money really goes, a Calendar with bills, paydays and spending on their day, Accounts and Debt for balances and payoff dates, and Search for finding any transaction.